When the SEC granted Dimensional Fund Advisors’ application to add ETF share classes to its mutual funds in November 2025, it cleared the way for a queue of similar applications from other asset managers. Nearly a year on, the industry is working out what it takes to run these funds day to day.
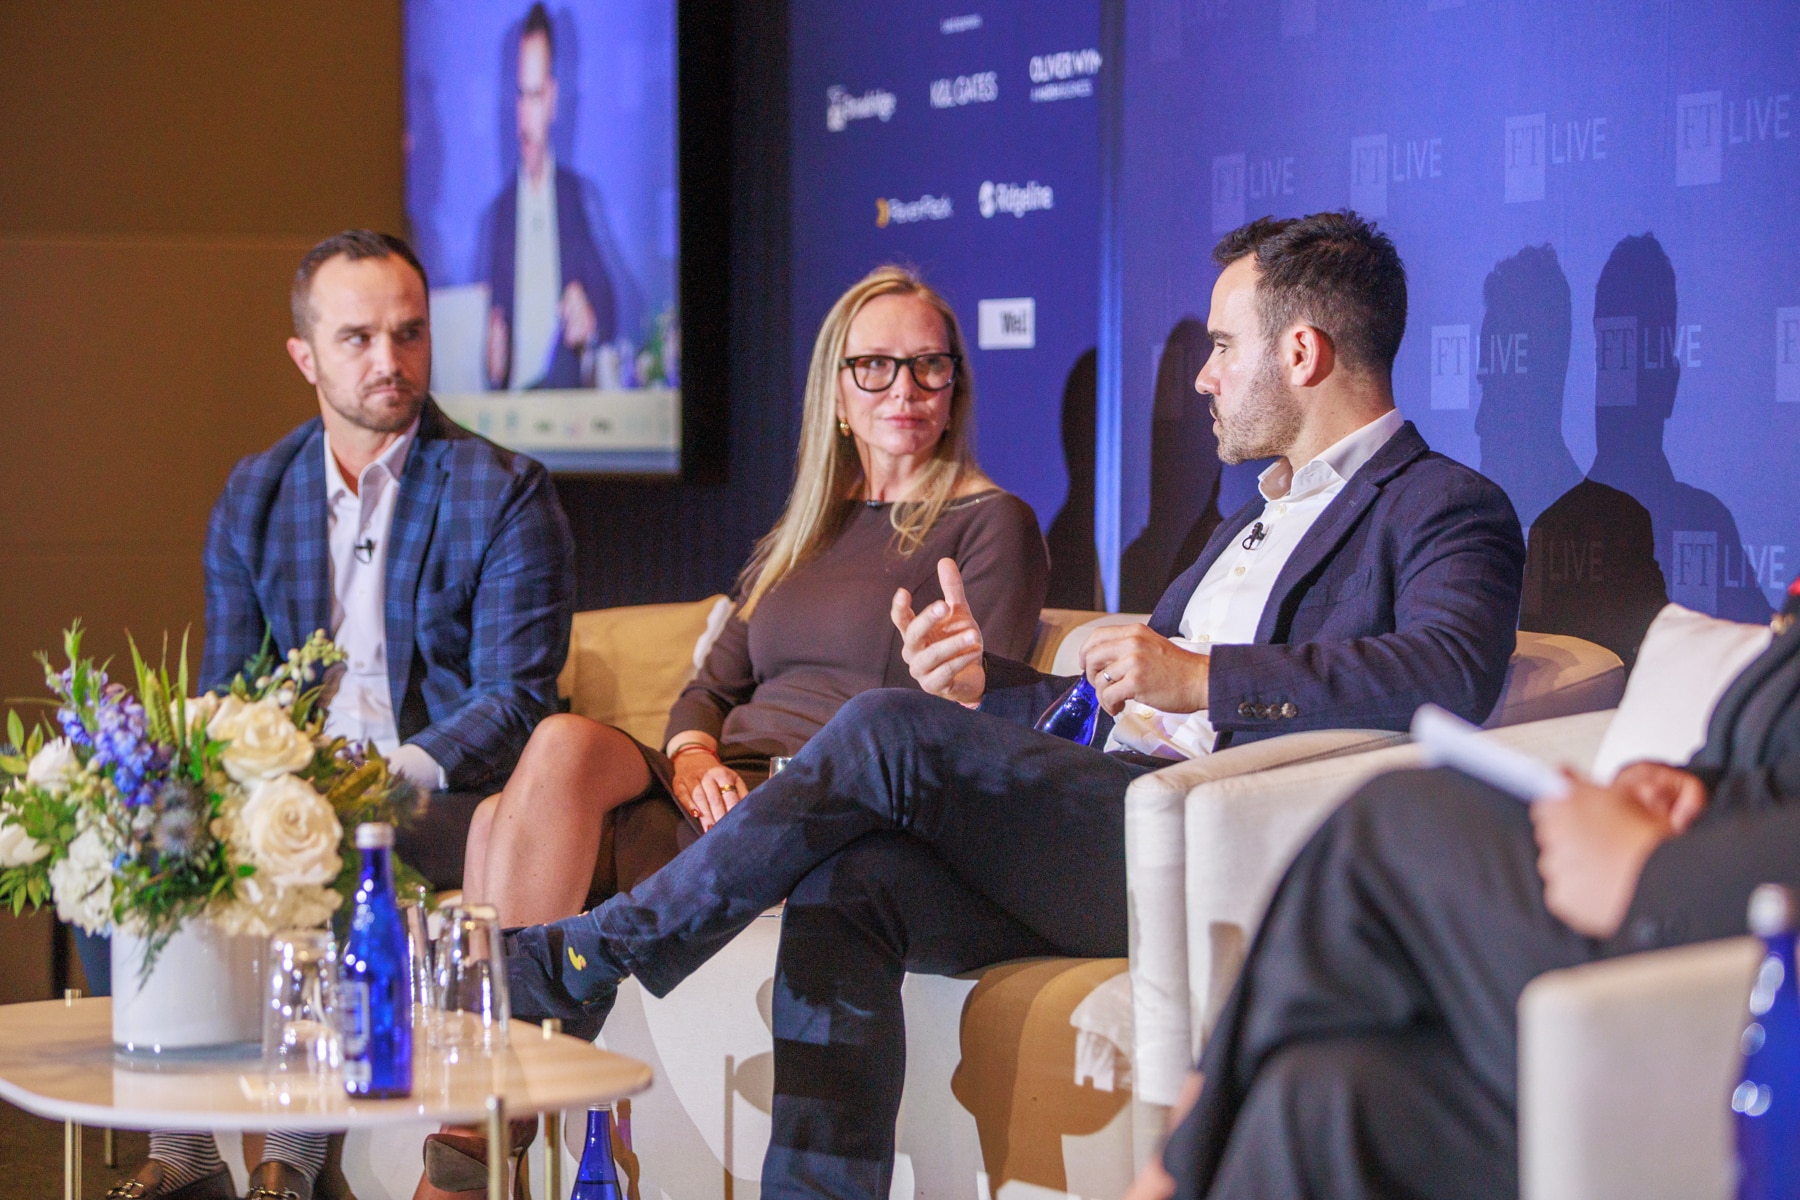
That was the subject of “Dual Share Classes: The Two-Way Wrapper Shift,” a panel at FT Live’s Future of Asset Management North America conference in Boston in October. FundGuard Sales Director Dan Vannucci joined other leaders in the space to discuss their thoughts and insights. Most of the panel came from distribution, so the conversation covered investor access, advisors and competition, while Dan, as he put it afterwards, “represented the technology and the product angle.”
The consensus Dan took away, which was also a theme across the wider conference, was that “operational complexity and technology complexity does present challenge to the ability to go to market.” This piece covers the panel conversation, why fund ranges end up split across systems and the value of a single investment accounting platform for mutual funds, ETFs and other structures.
What the Panel Said About Dual Share Classes
When the SEC began approving relief in 2025, some in the industry expected hundreds of new share classes. As one panelist put it, “it’s going to be quality over quantity,” with no “floodgate of share classes coming to market anytime soon.”
Dan thought the structure was worth the hype. In his conversations with asset managers, clients and prospects alike, he hears about a great new distribution channel and “so much operational friction.” “How do you support all this? Are your systems ready?” he asked the room. “And if your systems and your operations aren’t ready, then you can’t do it at scale in any way that’s going to make sense for your business.”
Another panelist made a similar point from the manager’s side. The relief has opened the structure to the industry, but “the backend still needs to be figured out” and the question now is “how do we do this at scale?”
The same panelist explained the appeal for an established active manager. Before the relief, the options for putting an existing strategy into an ETF were a conversion or a standalone clone, which “has become quite a dirty word in our industry,” and mutual fund holders who wanted the ETF had to sell and buy, which is a taxable event. On the other hand, a share class can let them move across in a tax-efficient way, though expectations still need managing. Adding an ETF class to a mutual fund with embedded gains “does not make that ETF tax efficient overnight,” because “those gains are shared across share classes.” The ETF class needs assets and redemptions before low-cost-basis shares start leaving the fund.
One panelist said appetite for active ETFs is greater than they’ve ever seen, but “the understanding of the complexity of a mutual fund with an ETF share class is not something that advisors are tremendously comfortable with just yet.” Another warned that changing the wrapper won’t rescue a strategy that wasn’t working. “The ETF wrapper is not a magic box,” they said.
Why Fund Ranges End Up Split Across Systems
The caution about scale comes from what sits behind a dual share class fund. Dan describes one portfolio, one pool of money, with mutual fund classes and ETF classes drawing on it. The mutual fund side is “cash in, cash out.” On the ETF side, “you’re dealing with participants, you’re dealing with shares, you’re dealing with unitization, you’re dealing with rebalancing.” On legacy systems, those become two different operating models with two different workflows around the same assets.
One panelist described what it took for a bank to be among the first to support dual share classes. It “required a significant amount of build,” including a single NAV calculation across share classes and creation and redemption processes that many mutual funds did not have, since “the in-kind nature of ETFs creates a new process for mutual fund share classes that for the first time are operating in kind versus cash.”
More operating models are on the way. Dan points to one raised at the conference, ERISA accounts, as ETFs find their way into 401(k)s and other retirement plans. He calls it “a third operating model,” with its own regulatory and governance framework and its own accounting structure for the platform to support.
For the past couple of decades, the standard answer to added middle and back office work was outsourcing, solving the problem, as Dan put it on the panel, “with more bodies.” Each new structure tended to arrive with its own workflow, team and reconciliation. And once mutual funds, ETFs and other products run on different platforms, Dan asks, “how do you have that view at the top of where your money is going in your investment strategies? You kind of can’t.”
Building ETF capability into an older platform can still leave those silos in place. Dan has seen this from the vendor side, on a legacy platform that had been around for 30 years without all the rules for ETFs. “So we had to build out the ETF capabilities,” he says. “But it’s still not unified.” On that platform, money allocated from a portfolio into a mutual fund and an ETF couldn’t be traced through to both. In his words, “you end up with operating silos even if you are doing it in one system.”
A Two-Way Shift in Fund Structures
The panel’s title came through in one panelist’s description of their own firm, “an ETF house” that is doing the opposite of most managers by creating a mutual fund share class for some of its ETFs “so that we would bring all the technology under one wrapper to serve different clients, including the retirement community, 401(k) plans and the like.”
Mutual funds are adding ETF classes, at least one ETF issuer is adding mutual fund classes and retirement plans bring requirements of their own. For investment accounting, fund type and share class type need to be settings on one platform, working from one set of securities, prices and books.
On FundGuard, fund type is configuration. Flagging a fund as an ETF switches on ETF orders and in-kind processing, while the fund shares one security master, pricing, corporate actions and set of books with the mutual fund range. Basket calculation, which often runs in a homegrown tool outside the accounting platform that has to be fed and reconciled each day, sits in the same investment accounting platform as the NAV.
An ETF share class follows the same route. It can be switched on for an existing mutual fund, with one class taking subscriptions and redemptions and another taking creations and in-kinds, both against the same portfolio. Since the classes share one accounting foundation, the mutual fund and ETF sides work from the same records, without a separate reconciliation team for each.
Different Rules for Different Products on the Same Securities
Sharing a portfolio means sharing securities, yet mutual funds and ETFs don’t always process the same securities in the same way. The panel’s point about tax efficiency shows why. The lots that leave a fund in an in-kind redemption are chosen by its lot relief method, which may need to differ from the method used for ordinary sales in the same fund.
On FundGuard, rules can differ by product and by transaction type. Sales can relieve lots on FIFO while in-kind redemptions use LIFO, within one fund and one set of holdings. Each fund view can also carry its own date and amortization rules, which is how daily NAV funds that correct forward and non-daily funds that publish on perfect knowledge sit on one platform.
In a dual share class fund, the classes share tax lots and holdings, so these rules have to apply inside one fund. Setting them per product and per transaction type lets the mutual fund classes and the ETF class each follow their own processing from the same records, with no second set of books to keep in line.
A Business Case Bigger Than Dual Share Classes
Dan is wary of building the case for a new platform around dual share classes alone. “I don’t think I would just do a business case just for dual share classes,” he says. In his view, asset managers aren’t replacing systems for a single structure, so “it has to be a bigger problem that they’re solving, which is preparing for the future. Otherwise, I just don’t think the economics are going to be there for a firm.”
Competition is part of the reason. As more managers offer ETF share classes in a crowded market, Dan expects them to become “table stakes.” One panelist made a related point about cost. Running a strategy as separate mutual fund and ETF products means two prospectuses along with legal, audit and board fees. As they put it, “fragmentation adds to cost.” The same can apply to the operations behind the funds.
Dan builds the wider case on three levers, “save money, make money and reduce risk.” A platform that takes on dual share classes and the next structure through configuration helps on the make money side, by answering the question “What other new products can I bring to market faster?” On the save money side, he would include the systems and processes that prepare a firm to adopt agentic AI, which he sees as “where I’m going to get the bigger lift” on operating model and technology costs, even though firms are wary of agentic AI today because of the risk. Risk is the hardest of the three to call. Taking people out of manual processes can reduce operational risk, but some firms may see AI as adding risk of its own.
What the Next Structure Needs From Your Platform
Dan kept coming back to the same theme on the panel. “Today, the complexity is dual share classes. It’s going to be something else tomorrow,” he said, adding that “there’s already another half dozen things out there that people are thinking about.” In his view, getting the technology and operations right is what lets a firm keep scaling and “be prepared for what’s next.”
The other panelists saw the infrastructure maturing. One expects support costs to come down once the industry learns what works, since “the first time is always going to be harder” and “once we understand the ideal support system, we can automate it.” Another sees distribution platforms as the next hurdle, because the platforms they talk to still ask issuers to choose one wrapper or the other. As that panelist put it, “We’re just not there yet.”
For operations teams weighing their next structure, a few questions show whether a platform is ready for it.
- Can mutual funds, ETFs and ETF share classes share one security master, pricing, corporate actions and set of books?
- Can processing rules differ by product and by transaction type on the same securities?
- Can a new fund type or share class be switched on through configuration?
- Can the next structure, whatever it turns out to be, run on the same platform without another specialist system?
Dual share classes are the structure in front of the industry now. The platform decisions made around them are likely to shape how quickly managers can take on the ones that come next.
See how FundGuard runs mutual funds, ETFs and ETF share classes on one investment accounting platform. Request a demo.
Frequently Asked Questions
What is a dual share class fund?
A dual share class fund offers mutual fund and ETF share classes on the same underlying portfolio. Following the SEC’s relief, mutual funds can add an ETF share class. At least one ETF issuer has filed to go the other way, adding a mutual fund share class to some of its ETFs.
Does adding an ETF share class make a mutual fund strategy tax efficient straight away?
Not straight away. Embedded gains in the mutual fund are shared across share classes, so the ETF class starts out carrying them too. The ETF class needs assets and redemption activity before in-kind redemptions begin moving low-cost-basis shares out of the fund.
Why do mutual funds and ETFs end up on separate systems?
The two products run different operating models on the same securities. Mutual funds take cash in and out, while ETFs work with authorized participants, creation units, in-kind baskets and rebalancing. Many legacy platforms were built around the mutual fund model, so ETF processing was added afterwards or run in separate tools, leaving reconciliation between them.
What does it mean for fund type to be configuration?
It means the investment accounting platform already supports the workflow for each fund type, so a fund is set up as one type or another. In FundGuard, flagging a fund as an ETF switches on ETF orders and in-kind processing, while the fund shares one security master, pricing, corporate actions and set of books with the rest of the fund range. An ETF share class can be switched on for an existing mutual fund in the same way.
Can mutual funds and ETFs use different processing rules on the same securities?
Yes, on a platform built for it. In FundGuard, rules can differ by product and by transaction type, so ordinary sales can relieve lots on FIFO while in-kind redemptions use LIFO in the same fund. Each fund view can also keep its own date and amortization rules.
Is an ETF share class launch enough to justify a new investment accounting platform?
Usually not on its own. FundGuard’s Dan Vannucci expects ETF share classes to become table stakes and sees the stronger business case in preparing for the structures that follow, which means bringing new products to market faster and lowering operating model and technology costs, including through AI adoption.
What should an investment accounting platform offer for the next fund structure?
It should hold mutual funds, ETFs and share classes on one security master, pricing, corporate actions and set of books, with processing rules that can differ by product and by transaction type. New fund types and share classes should be added through configuration, so the next structure doesn’t need another specialist system.